An industry getting back on its feet, slowly
When the Collins Dictionary chose ‘permacrisis’ as their word of the year in 2022, they might have had leisure and hospitality in mind.
Few industries have been as heavily impacted first by Covid-19, followed swiftly by the global cost of living crisis.
Businesses are also feeling the impact of new technologies and competitors, from sharing platforms to fitness trackers.
Consumer preferences are changing fast, making it hard to keep pace and maintain customer satisfaction.
How is the sector adapting?
We wanted to find out how businesses are coping in the face of these challenges – and also where they see the opportunities emerging that can lead to growth over the longer term.
Our survey includes a broad cross-section of traditional leisure and hospitality businesses, as well as providers of in-home entertainment, such as gaming.
- When: September-October 2022
- Who: 600 senior decision makers, including CEOs, risk managers, operations managers and compliance managers.
- Where: Countries across Europe, North America, Asia-Pacific and Latin America.
- Sectors: Hotels and accommodation; health fitness and wellbeing; venues and visitor attractions; bars, pubs, nightclubs, cafés and restaurants; gaming and gambling; media and entertainment.
- Size: 99% of companies with annual revenue over $300 million, 1% between $100-300 million.
Key findings
Post-pandemic recovery still a work in progress
Covid-19 hit traditional leisure and hospitality hard. 44% of respondents said risk-related losses were higher or much higher than expected over the last two years.
Businesses in our survey are still feeling the long-term impacts, including a skills gap from staff leaving the sector (47%) and the shift to leisure activities at home (45%).
Switch to digital will be pandemic’s greatest legacy
The pandemic may have provided a spur for companies to embrace new technologies and create innovative new offerings.
Almost three-quarters (70%) said that an accelerated switch to digital first will be the greatest long-term legacy of Covid-19.
Greatest opportunities for the leisure and hospitality sector over the next 2 years
Download Global Leisure and Hospitality Risk Outlook Report
Is your business reputation-risk-ready?
Benchmark your business against 850+ leisure and hospitality companies on a defined standard in reputational risk research.
Related content
Profitability is higher strategic priority than growth
With the global cost of living crisis following hard on the heels of the pandemic, it’s not surprising that company strategies are more focused on improving margins (46%) and growth through acquisition (48%) than on organic sales growth (35%) over the next two years.
Businesses feel risks are not within their control
The sense of permacrisis in the industry may be making it harder to manage risks. Only 28% said the root causes of their risks were somewhat or completely within their control.
Interestingly, almost three-quarters (74%) said they lacked the data or knowledge they needed to address their risks.
Competition from tech-savvy entrants is hotting up
From home delivery apps to fitness trackers, new providers are looking to disrupt traditional leisure and hospitality business models and eat into market share.
More than half (52%) of our respondents said increased competition from outside the sector was among the greatest obstacles to achieving their strategic objectives.
Firms struggle to keep up with changing tastes
Younger consumers want new experiences and Instagram-able moments, both online and in person, which can be challenging to deliver.
This may explain why changing customer tastes and preferences were the second greatest obstacle to achieving strategic objectives (42%).
74% of survey respondents said they lacked the data or knowledge they needed to address their risks
Reputational risk is rising up the agenda
A majority of businesses (59%) now measure and monitor their reputation to help identify and prevent potential threats that could tarnish their good name.
46% think having insurance for reputation risks is necessary and 22% say it’s mission critical.
Greatest risks to businesses’ success in the next 3-5 years
59% now measure and monitor their reputation to help identify and prevent potential threats
Frontiers of new technology
- Offering tech-enabled customer experiences: more businesses will use tech, such as virtual reality and the metaverse, to create realistic tours pre-visit and personalized on-site experiences.
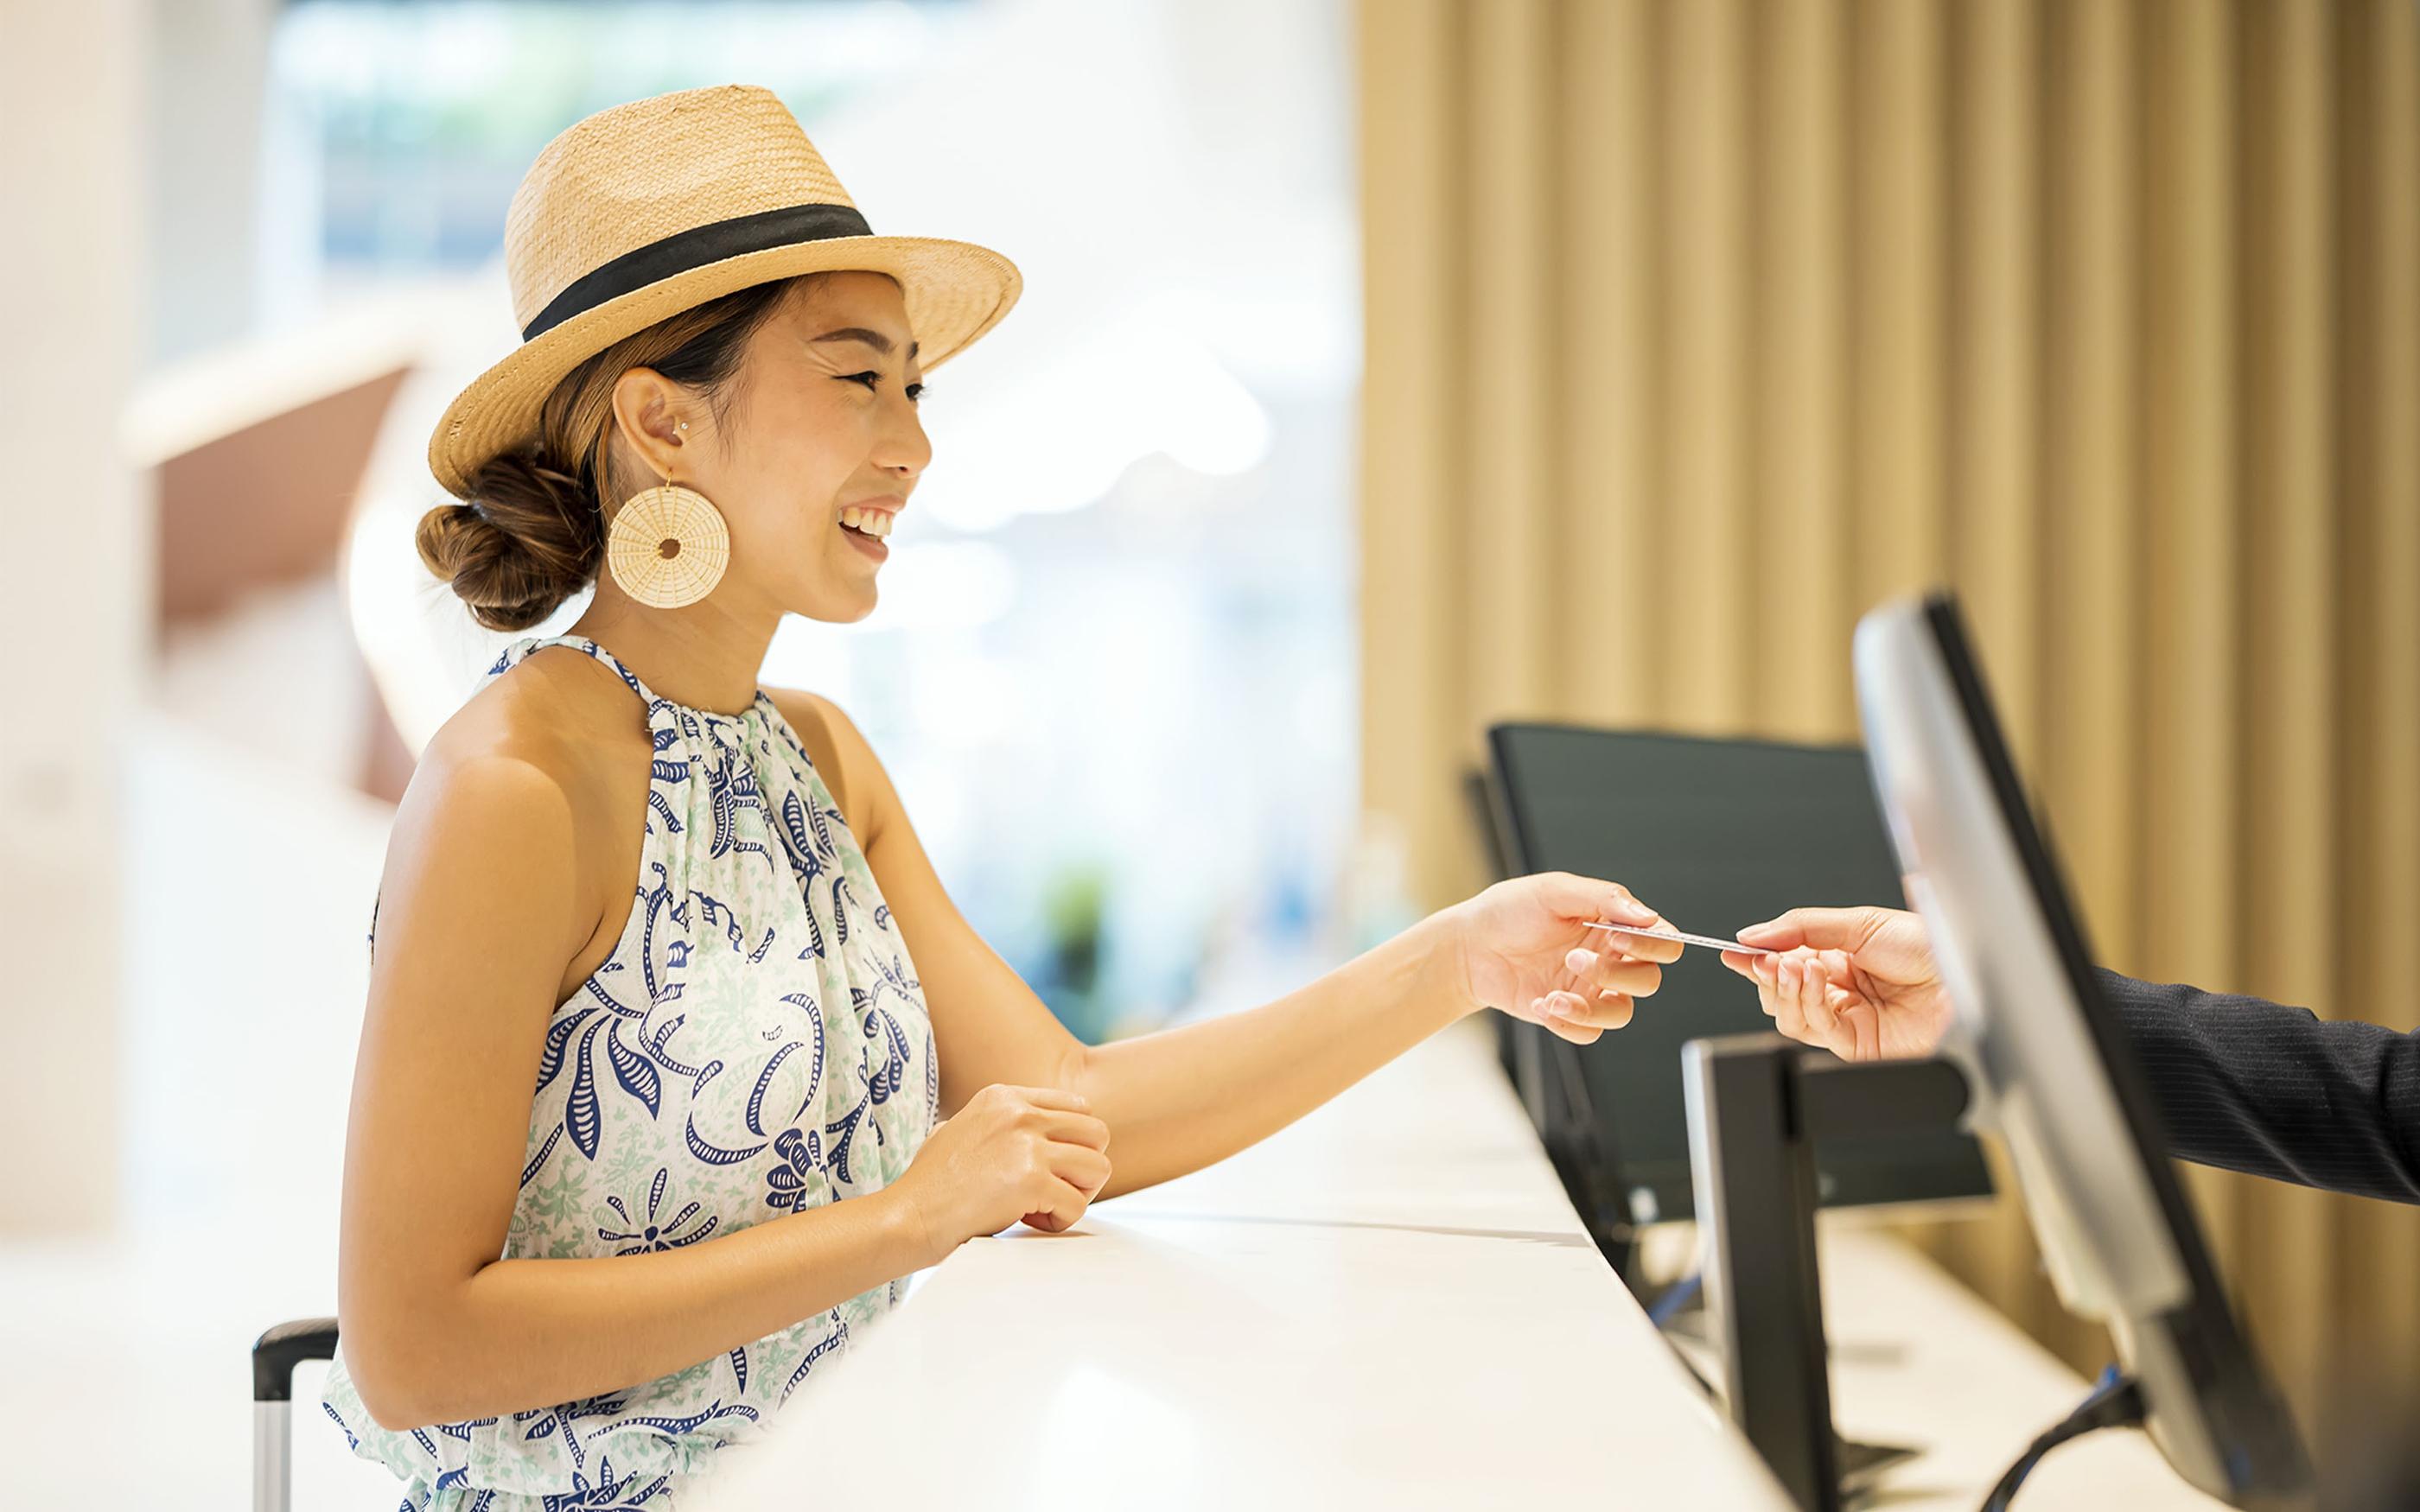
- Making it frictionless: we’ll see more use of artificial intelligence to simplify booking and payment and RFID for keyless room access in hotels. With competition proliferating online, firms will also look to simplify apps and websites to improve the online experience.
Transformation of people and workforce
- Improving the employee experience: firms will need to do more to recruit and retain staff, creating work that feels more meaningful and rethinking recognition and reward schemes.
- Blending automated systems and staff: finding the right balance between people and technology will be key – for example, using self-pay tablets in restaurants could free up staff to offer a better service to customers.
Changing consumer preferences
- Bridging the demographic gap: the generations increasingly want very different things as younger consumers chase Instagram-able moments and new experiences, while older consumers require safety adaptations or mobility support. The increased desire for sustainable options is also influencing decisions for younger consumers.
- Scaling to meet changing demand: hybrid working and changing lifestyles will continue to affect how and where people spend in cities, suburbs and online. Businesses may find it increasingly difficult to scale up and down to meet changing demand.
Sustainability and ESG
- Planning for climate impacts: we’re seeing heatwaves, wildfires, storms and floods in areas that never had them before. Businesses need to plan for these events happening on a regular basis.
- Getting ahead of climate regulations: more businesses will make net zero commitments and report in line with the Taskforce for Climate-related Financial Disclosures (TCFD). Initiatives to reduce plastic and food waste will also increase.
- Emerging focus on water and biodiversity. While climate has tended to receive most attention to date, concerns related to water and biodiversity will become more prevalent over time, especially for assets that are in areas of high water scarcity or biodiversity hotspots, or that have large footprints.
- Integrating ESG into risk and materiality efforts: as with many industries, risk leaders are incorporating ESG risks into their risk planning efforts, often expanding a generic ‘ESG risks’ labels in materiality summaries into detailed risk (and opportunity) descriptions that are specific to their business.

Download your report
To learn more, download your free survey report by completing the short form at the top of this page.
Disclosure
WTW offers insurance-related services through its appropriately licensed and authorised companies in each country in WTW operates. For further authorisation and regulatory details about our WTW legal entities, operating in your country, please refer to our WTW website. It is a regulatory requirement for us to consider our local licensing requirements.
Contact