The general aviation insurance market is navigating an unusual phase. While capacity remains abundant and competition intense, insurers are increasingly managing the tension between protecting short-term income and maintaining long-term profitability.
The result is a market that appears outwardly soft, but beneath the surface displays significant inconsistencies in underwriting behavior, renewal outcomes, and strategic direction.
MGAs: transforming the dynamic?
One of the most notable developments over the past 12 to 18 months has been the migration of experienced underwriters between established insurers and, more recently, into newly formed Managing General Agents (MGAs). Movement of underwriting talent is not a new phenomenon, but the growing number of specialist aviation MGAs entering the market has introduced a fresh dynamic.
When an underwriter moves between established insurers, there is typically some disruption, but pricing discipline and portfolio expectations often remain relatively consistent. However, when experienced underwriters join established or entirely new MGA platforms, the incentives can be markedly different. New ventures frequently face pressure to build premium volume, establish credibility, and develop meaningful market share within a short timeframe. This can create aggressive pricing strategies and broader risk appetite, although approaches vary considerably depending upon the objectives of the MGA and the requirements of its capacity providers. As these new participants seek to attract business and establish portfolios, downward pressure on premium levels can emerge, particularly on well-performing accounts where competition is already strong.
This trend forms part of a broader shift in the aviation insurance market. Capacity is increasingly fragmented across traditional insurers, specialist MGAs, delegated authority structures, and facility-backed solutions. This gives brokers and clients access to more options than ever before, but it creates additional complexity in ensuring the long-term commitment of individual market participants.
Facilities: The rise continues
The increasing use of facilities remains one of the most significant structural developments in the current aviation insurance marketplace.
Many brokers continue to invest heavily in lineslips, binders, auto-binding arrangements and other delegated authority solutions designed to deliver efficiency, certainty of capacity, and a streamlined placement process. The largest intermediaries now operate multiple facilities across various aviation disciplines, allowing significant volumes of business to be placed outside the traditional open market process.
For clients, facilities can provide certainty of capacity, simplified renewals and access to competitive terms. For insurers, accessing business via a facility reduces distribution cost and administrative workload, both of which are part of a business acquisition cost formula. However, the growth of facility business can reduce the volume of risks available to the open market, creating additional competitive pressure among insurers seeking to maintain premium income.
This has contributed to market turbulence, particularly among longstanding aviation insurers. Some are focused on maintaining existing positions, while others are actively seeking to build market share or defend their relevance in an environment where facility participation increasingly dictates access to business. The emergence of new MGA capacity compounds the challenge, placing additional pressure on established insurers to remain visible and competitive.
LTAs continue to evolve
Long-Term Agreements (LTAs) remain available across many general aviation placements, although they are less prevalent than in previous years and increasingly include underwriting caveats, review provisions or pre-agreed adjustment mechanisms.
For insureds, LTAs provide budgetary certainty and protection against sudden market fluctuations. For insurers, they offer continuity of premium income and the opportunity to build long-term relationships with policyholders.
This approach potentially allows clients to benefit from the annual renewal cycle
Hedging is also a feature of the current marketplace, with only a percentage of an account placed on a multi-year basis. This approach potentially allows clients to benefit from the annual renewal cycle if the pricing environment continues to soften, while limiting the exposure of the overall placement if the market moves in the opposite direction.
However, market acceptance of LTAs is far from uniform.
One recurring theme of recent renewal seasons has been the inconsistency with which individual insurers approach annualised rate reductions that have been a feature of multi-year agreements. While some insurers continue to support downward pricing trajectories for years two and three of an LTA, others are showing less enthusiasm for rate breaks during an agreement’s lifecycle. This is particularly apparent where changing market conditions or portfolio performance have the potential to alter medium-term profitability.
LTAs remain available and attractive, but their implementation requires careful navigation, and early engagement with insurers to ensure expectations remain are aligned throughout the life of the agreement.
Competition intensifies in a global insurance marketplace
Meanwhile, technology, data accessibility, and more globalized distribution networks continue to reshape the competitive insurance landscape.
Clients now have access to a broader range of insurers and brokers than in previous years. Likewise, insurers can engage with opportunities across multiple geographies without necessarily maintaining a significant physical presence in every region. While these developments have undoubtedly improved efficiency, they have also intensified competitive pressures.
In a softening market environment, insurers facing rate reductions on existing accounts inevitably seek new business opportunities to offset declining revenues. The result is heightened competition for attractive risks, greater pricing volatility, and increased workload across all participants in the insurance chain. The pressure to capture new business has therefore become increasingly evident.
Regional insurance hubs also play an increasingly important role in this environment
Regional insurance hubs also play an increasingly important role in this environment. Insurers in countries including Australia, France, Germany, Singapore and the United States continue to defend local portfolios vigorously while simultaneously competing for international business opportunities. This overlap of regional and global competition can distort pricing behavior, particularly where insurers are seeking to achieve strategic growth targets or maintain premium volumes within defined territories.
Soft market conditions persist, but not equally
Despite ongoing competitive pressures, not all segments of the general aviation market are experiencing the same levels of rate reductions.
Larger premium-bearing accounts continue to attract the greatest level of competition and therefore the most significant opportunities for rating adjustment. Insurers remain eager to secure meaningful premium volumes, particularly where loss records are favorable and risk management standards are demonstrably strong.
Conversely, lower and mid-premium accounts often experience more modest movement. While these risks benefit from the competitive conditions, the magnitude of potential reductions can be considerably less pronounced once acquisition costs, operational expenses and underwriting resource requirements are considered.
Similarly, accounts with lower limits can attract insurers able to deploy larger lines and secure a greater share of premium on each risk, despite the lower potential portfolio-level impact of an individual claim. This has an impact upon increased competition as 100% of a given risk is placed more quickly.
This divergence highlights the underlying challenge facing many insurers. While market conditions encourage competitive pricing, the long-term profitability of aviation portfolios remains a key consideration. Inflationary pressures, the rising costs of claims, and broader economic uncertainty continue to influence underwriting decisions, even as clients seek budget relief and insurers compete aggressively for market share.
Emerging opportunities in drones and AAM
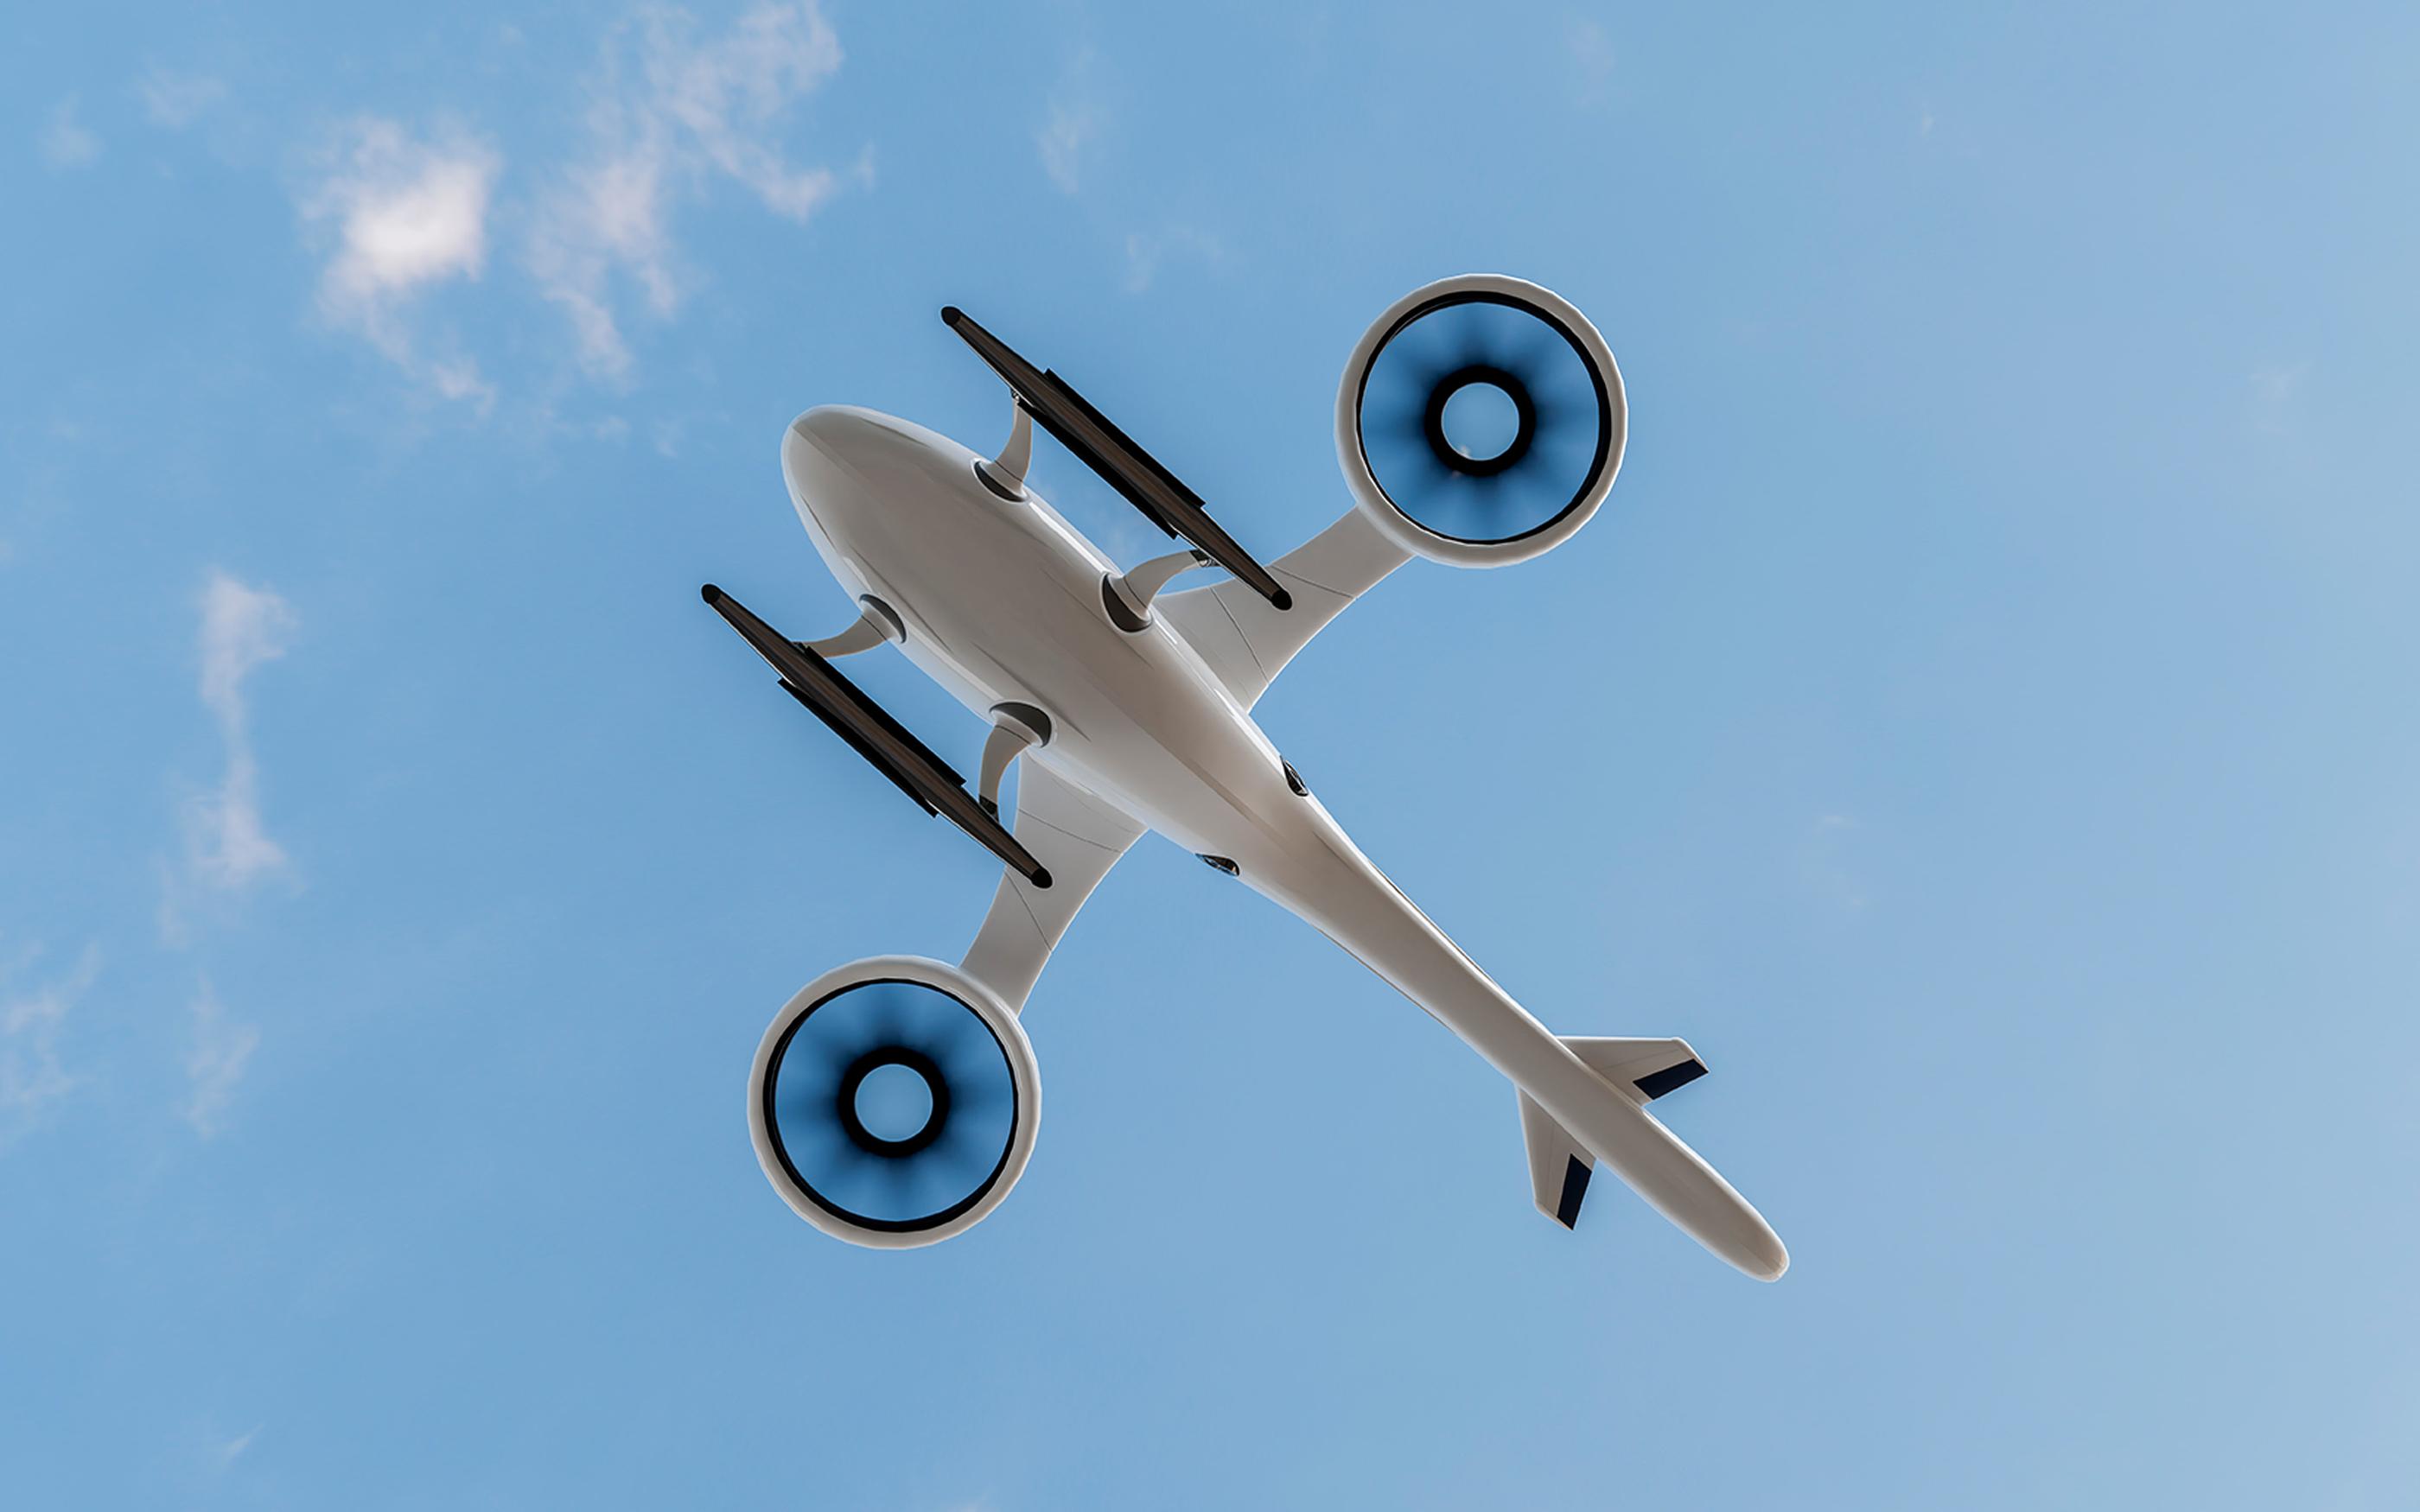
Drones and advanced air mobility (AAM) remain among the most significant emerging growth opportunites within aviation insurance.
Commercial drone use continues to expand across infrastructure inspection, logistics, agriculture, emergency services, and a growing number of industrial applications.
At the same time, investment in electric vertical take-off and landing (eVTOL) aircraft and broader AAM ecosystems is attracting substantial interest from manufacturers, operators, and investors. Explore how insurance can help shape eVTOLs and future flight.
These sectors represent significant potential premium pipelines, particularly across China and some other Asia-Pacific markets, selected parts of the Middle East and the United States, where development and investment remain strong.
Specialist MGAs have been particularly active in this segment, often demonstrating greater agility and willingness to develop bespoke insurance solutions compared to traditional insurers. The ability of MGAs to move quickly and adapt products to emerging technologies has allowed them to establish a strong presence within this developing market.
As the sector matures, financial sustainability will become increasingly important
However, clients and brokers continue to place considerable value on scale, balance sheet strength and long-term commitment. As the sector matures, financial sustainability will become increasingly important, and insurers will continue to evaluate which participants possess the infrastructure, technical expertise, and fiscal backing to support the industry's growth over the long term.
Education remains critical. New technologies introduce new exposures, regulatory challenges, and operational considerations. Underwriters, brokers, and clients alike must continue developing specialist knowledge to ensure insurance programs evolve alongside the underlying technology
Claims trends and maintenance challenges
On the claims side, maintenance-related losses remain an area of growing concern.
Several interconnected factors are contributing to the increase in maintenance-related losses. Inflationary pressures have increased the cost of aircraft parts and repairs. Supply chain disruptions continue to affect the availability of raw materials and components from original equipment manufacturers (OEMs) and other suppliers.
Meanwhile, the industry continues to face a shortage of skilled maintenance personnel, particularly experienced engineers and technicians.
These challenges can elongate repair periods, increase maintenance costs and create greater operational pressure on operators seeking to ensure fleet availability.
An ageing aviation workforce further compounds the problem. As experienced personnel retire, organizations must balance training the next generation of talent while maintaining operational standards and safety performance. Although the industry continues to invest heavily in workforce development, the gap between experienced personnel leaving the sector and new talent entering it remains a challenge across many regions and many parts of the aviation industry as a whole. Explore the challenges facing aviation's workforce.
From an insurance perspective, these trends reinforce the importance of maintenance quality, documentation, training, and operational oversight. As repair costs continue to increase, even relatively routine incidents can generate claim values significantly higher than historical norms.
Looking ahead
The general aviation insurance market remains well capitalized and highly competitive, but the forces shaping it are becoming increasingly complex. The growth of MGAs, the expansion of facility business, the evolution of LTAs, the emergence of drone and AAM opportunities, and the persistent claims inflation all point toward a market undergoing structural change rather than simply following a traditional soft market cycle.
For clients, these conditions continue to present opportunities to secure favorable outcomes. For insurers, however, the challenge remains balancing growth ambitions against underwriting discipline and long-term sustainability.
As competition intensifies and new market participants emerge, maintaining consistency, technical expertise, and a clear strategic focus will be critical to navigating the next phase of the general aviation insurance cycle.
Willis General Aviation is holding a safety forum with colleagues in the Aviation Safety Partnership in London in September 2026.
This inaugural forum brings together our entire commercial general aviation community, from rotary operators and business jet organizations to underwriters, regulators, legal professionals, and safety service providers, to drive meaningful dialogue on safety innovation and risk management. Hear from thought leaders, engage in technical and strategic sessions, and connect with the people defining the future of general aviation safety.
Places are limited. Register now to secure your place.
Disclaimer
WTW hopes you found the general information provided here informative and helpful. The information contained herein is not intended to constitute legal or other professional advice and should not be relied upon in lieu of consultation with your own legal advisors. In the event you would like more information regarding your insurance coverage, please do not hesitate to reach out to us. In North America, WTW offers insurance products through licensed entities, including Willis Towers Watson Northeast, Inc. (in the United States) and Willis Canada Inc. (in Canada).