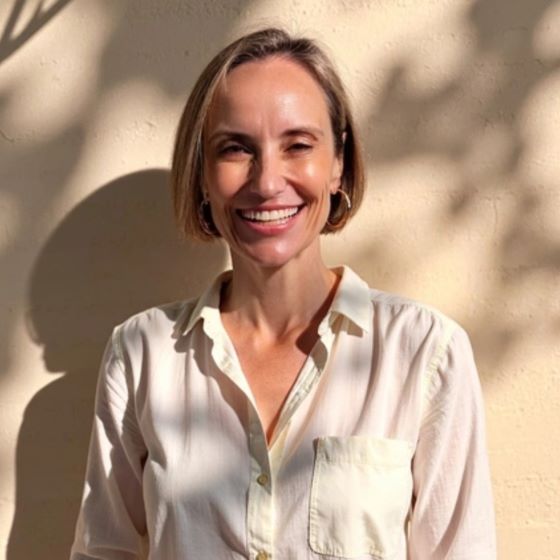
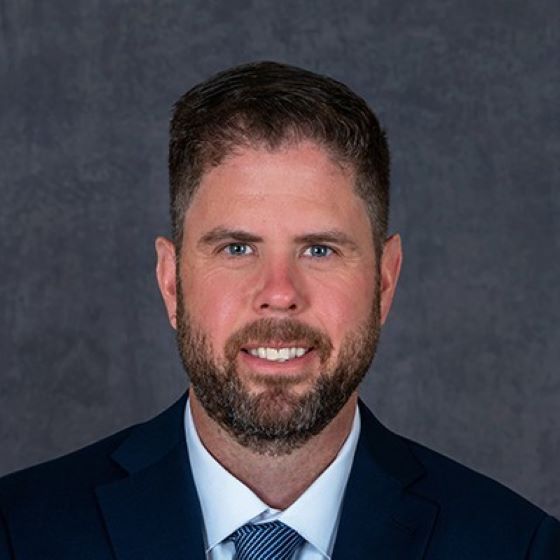
In this episode of The Via Benefits Exchange, Nina Krammer sits down with Josh Miley, ICHRA Solution Leader at Via Benefits, to break down what an Individual Coverage Health Reimbursement Arrangement (ICHRA) is and why employer interest is accelerating. Josh explains how ICHRA enables a defined contribution approach to healthcare, giving employees more choice while helping employers manage costs and risk. The conversation explores common misconceptions about the individual insurance market, tax efficiency compared to cash stipends, and real-world savings employers are seeing. Learn how organizations can start small, test ICHRA by employee class or location, and prepare for future benefits strategy shifts with support from Via Benefits by WTW.
Transcript for this episode
Nina Krammer:
Welcome to The Via Benefits Exchange, a podcast where we share the latest market trends, legislative updates and exchange of ideas for employers, plan sponsors and consultants looking to simplify healthcare benefit administration, reduce benefits related costs and liabilities, and elevate spending account offerings to employees and retirees.
Nina Krammer:
Today we have Josh Miley, solution leader of Via Benefits Active with WTW joining me. Hi Josh.
Josh Miley:
Yeah, thanks for having me.
Nina Krammer:
Yeah, absolutely. Before we get started, can you introduce yourself beyond just your title, what it exactly is you do and your background to our listeners?
Josh Miley:
I've been with WW for about 25 years now. Most of that time spent in the large group consulting and brokerage space. Over the past year I joined Via Benefits on the individual marketplace side to build out our ICHRA solution, which sits inside of our active business. What that means is, and what we are doing today is similar to what we've done for two decades on the retiree side, which is convert those individuals from group benefits to the individual marketplace. We are now doing that for active employees as well. So my job is to build, manage, maintain, sell, and grow our active business, which is largely ICHRA.
Nina Krammer:
So you mentioned ICHRA, that's an acronym. What does that stand for? What does it mean exactly?
Josh Miley:
ICHRA stands for Individual Coverage Health Reimbursement Arrangement, or it's the HRA that we all know with IC in front of it. For individual coverage, it went live 1.1.2020. What that allows employers to do is put tax free or tax preferred dollars into a notional account, which is the HRA, and with those dollars, individuals can purchase individual healthcare. So what we would think as either healthcare.gov plans or maybe individual plans that are sold in states by insurers in those states, the employees can take the dollars from the fund, from the ICHRA and purchase those individual coverage insurance plans. It allows employers for the first time to do defined contribution for healthcare. They're fixing their subsidy into an account and they're allowing those employees to go shop for healthcare. So it's really revolutionary in terms of a fundamental change in the delivery of benefits and we're seeing that for the first time and large employers are starting to adopt interest in it.
Nina Krammer:
Yeah. You just mentioned it was introduced in 2020 or went live. Yeah. And you're now hearing more employer interest. Yeah. Why do you think ICHRA is gaining traction now among employers
Josh Miley:
Six years past kind of it going live? The trajectory essentially is this, it was passed in late 2019, went live in 2020. The world that we all knew in 2020, a lot of things going on at the time, I don't think many employers were thinking about fundamentally changing the delivery of benefits during 2020 and 2021. What we saw kind of coming out of that early phase, about 2022 and 2023 was small employers that offered ICHRA because they didn't for when they were offering benefits for the first time, chose ICHRA instead of a group sponsor plan. If you think about it, if you could avoid wading into the complexity of what's my insurance coverage? Who's my broker? What compliance things do I have to do, how do I administer this, how do I set up the payroll functionality? If you could bypass all of that and say, I'm putting dollars into an account, go shop or employer for the first time, that would be what you would set up.
Josh Miley :
So what we saw in 2022 and 2023 was really employers offering ICHRA, typically smaller employers. 'cause they were offering benefits for the first time and that was the easiest way to do it really in that 2024 timeframe up until the past year was, I would say, interest by large employers. Like why are these small employers doing this and should I think about it? And then over the past year that interest by large employers have turned into action, which is doing due diligence on ICHRA, trying to understand does it fit if it does, where and why? Uh, and maybe making a strategic glide path over the next year, two years, three years to scale into ICHRA maybe for portions of their population. Kind of started slow because of COVID and then started in the small employer space and now is expanding into the larger employer space.<.p>
Nina Krammer :
Talk a minute about the individual insurance market. We hear a lot in the news about the impact of tax credits or carriers changing where they're offering a plan for someone who doesn't really understand the individual market. Describe it at a high level.
Josh Miley :
You hear debates about the tax credits and the affordability that it may provide. It's often viewed as the insurance of last resort, meaning I have benefits through my employer, so why would I want this thing? Because I get my own benefits to my employer. That must be bad that what I have must be good. In reality, the individual market in any geography typically has anywhere between three carriers up to 7, 8, 9 carriers in a geography may have anywhere between 20 plans up to, in some cases 120 plans in a geography. So a lot of choice despite what happened this past year with premiums going up, that went up significantly because of a one-time change with the tax credits. Outside of that, a lot of stability. So there's 24 million give or take, individuals pre-Medicare that are on the individual market. That lends itself to typically a lot of stability when the government isn't changing things with tax credits.
Josh Miley :
And then you typically, as an employer hear mixed things about the individual market because it's serving different needs and there's different players in it. What I mean by that, there are individual market only insurers, Oscars of the world and betters of the world that do a really good job in the individual market and are super competitive. And then you look at other insurers that traditionally play on the commercial or the group side, that being United and Aetna and the Blues and Cigna and others, and I think they're in a little bit of a mixed boat, they stand to lose if an employer goes to the individual market where Oscar and Ambetter only stand to gain, it's got plenty of options for employees and employers to ultimately provide benefits to their workforce. So a lot of the perceptions we hear about it are negative. A lot of the opinions we hear about it are skewed based on who was telling you that opinion. The reality of the individual market's much better than the perception of it.
Nina Krammer :
So setting aside the perception or maybe misconceptions about it, I would imagine given in the business that we're in, that there's a cost saving strategy to it. Mm-hmm
Josh Miley :
The ICHRA the the account itself is an ERISA group plan similar to what an HRA would be or an HSA would be. Group plans. You file a 5,500 form for them, you have a plan document for them. There's an SPD for them. That is your obligation as an employer. That is the group plan because it is set up as a group plan. It also provides the pre-tax subsidization in the ICHRA. If I give my employee $500 in cash, that becomes a taxable event to the employee. I put $500 into an ICHRA subsidy. It is not, it's treated just like it would be under the group employer health side today. 'cause it is the group plan. What is not a group plan are the individual insurance options. Those aren't related to the employer at all. Employer can't say, Hey, I want a new plan or I want you to rate this plan differently.
Josh Miley :
They're disconnected, they're severed from managing that side of it. So a lot of interesting things happen on the individual marketplace when we looked across essentially about 1600 employers and about 16 million individuals in 2025. And we compared all of their group costs. So the plans they have today on the group side and compare that to the individual market to say, what if this person in state X went from a group plan to an individual plan, accounting for their utilization, their deductibles, their copays, and the premium of the plan itself, what would actually happen? And when we looked at that across those 1600 employers, about 16 million employees or members, we saw savings on average of about 12% across all 50 states. Both geographies that are air quote good for ICHRA individual market. And those that aren't on average the savings was 12%. Where does that savings come from?
Josh Miley :
The savings come from a couple of different areas. One is competition. As I mentioned upfront. You have individual market insurers only. They are very sophisticated in how they price their plans. They fully recognize that if there are two plans side by side that seems similar. And while brand may be important, maybe I've recognized the brand of carrier one and not brand of carrier two. If I could get the exact same thing for a penny less, why wouldn't I take the one that's a penny less
Josh Miley :
When I do a narrow network as an employer, I'm doing a narrow network for all 10,000 or whatever of my employees and there's gonna be winners and losers in that. That's a decision I'm making that's gonna disadvantage people on the individual market. If you're with a carrier in a state and there's six carriers, let's say all six of them offer a narrow network, what you can do on our platform is you can put in your drugs and your doctors and it'll search across all six carriers and all a hundred plans. So while maybe all six of them offer a narrow network, the combination of the six of them, you're gonna find the doctor that you want. You're gonna have the drugs covered that you need to have covered. But what's happened is you've released the value of those narrow networks to those employees and you get some interesting things come outta that.
Josh Miley :
For instance, here where I live in the Philadelphia market, there's a hospital that has an insurance product while a large national employer probably is gonna contract with that hospital's insurance product. 'cause now that's a one-off contract that they have just in the Philadelphia market and they're trying to administer benefits across 30 states. The individual market releases that value immediately to now I can contract with that hospital systems insurance arm and I'm getting the best possible value I can get to go seek care at that hospital. So it releases value that way. The third big one that I would put out there is on the group side, when you enroll through your employer, you and your family are enrolling together. When I take my employer's PPO plan, my wife and children come with me on the individual market, I still can do that. But I can also decouple it.
Josh Miley :
I could take carrier a's gold plan. My wife could take carrier B'S silver plan and my children who are both college age could enroll in whatever the health plan is that their university offers. So what I've done there is I've now optimized the purchase for my family in a way that I can't do on the group side. That also frees up costs in the market as well because my children have taken plans that are right for them. I've taken plans right for me, we're not all over-insured and the insurance market's not trying to price for everyone being the same. And they priced for me in that plan. They priced for my kids in that plan, premiums are better aligned to people narrow networks while scary are not because they provide coverage for everyone and the competition really does drive savings. So the combination of those things, there's not one singular answer there. The combination of those things provide real value to both us as shoppers and as employees provide some value to the employer who may be trying to save money.
Nina Krammer :
You mentioned earlier that just in the past year that employers have really started evaluating it or large employers and that just now they're starting to really pick up adoption with that. Are you noticing any early trends among these employers? Whether it's in terms of size?
Josh Miley:
I think my original hypothesis would've been a year ago that certain industries are probably not a good fit and others are maybe we naturally say healthcare industry is a bad fit and maybe retail industry is a good fit. As we've gone through this with employers that doesn't necessarily prove out to be correct. What type of cost pressure are you under as an employer? We all make New Year's resolutions
Josh Miley :
And if you already put them in and you still have a 10% increase, I don't really know what your answer is unless you think about something fundamentally different. The first driver is generally, am I under cost pressure is one, two is, am I being challenged by leadership to do this differently? If you think about the complexity of healthcare, one of the big questions we get often is can't AI fix this? Can't AI make my brokerage relationship better? Or can't AI make enrollment easier? Can't AI solve? Whatever the problem is. And healthcare is messy. So if you don't shift to a different model and that model is I give you money and then you shop. If you think about the counter to that, which is the world we all live in today, do we honestly think AI is gonna magically fix that for an employer?
Josh Miley :
Probably not. But when you get down to here's dollars, here's shop that starts to resonate with employers 'cause they understand how that drives efficiency. So am I looking for cost savings? Am I looking for efficiency savings? And then I would say the other ones are gonna generally be what is my overall relationship with my workforce and how do the benefits play in that? Meaning do I provide very, very rich benefits today? How do I communicate benefits? Am I communicating benefits as an extension of us being a paternalistic family And what words am I using? What phrase am I using and am I surveying employees around their engagement? Whether the math says it's right or not, not. That may not be the employer that's like, Hey, I'm gonna be the first one to do this. So that, that would be three. And then four is is ultimately gonna be where are you and where are your employees?
Josh Miley :
If you have a hundred employees across 50 states, that's gonna be really hard because you're tapping into insurance markets that are unique to each one of those states. If you have a manufacturing location, a call center, distribution center, some large portion of a population that's in a state or a handful of states, icra could make a lot of sense 'cause you can drive value because we can quantify what the purchase of insurance is in that state. And you can move a lot of individuals in that state to the individual market depending on where you are on the cost continuum, depending where you are with your relationship with employees, depending on how many people you have, where the combination of all those things could suggest whether ICHRA is a good fit for you now or whether you should wait to see how the market evolves. And we have plenty of tools and resources that we offer to employers, help them make those decisions.
Nina Krammer :
One of the things you mentioned with cost pressures and previously you mentioned for participants that they're seeing on average about 12% savings. What about from an employer standpoint? Are you seeing any kind of data there?
Josh Miley :
The 12% actually is is just a savings number. How you share in that is is up to the employer. So what that's looking at is saying the cost of insurance on the individual market, apples to apples, not shifting costs but like could I buy the same thing that's about 12% less a number of things that employer could do there. They could simply fix their costs and say, I'm not changing my air quote deal with an employee today. I'm, I'm subsidizing it the same way and now I got all 12% of those savings. Or they could say, we know this is a transition year and this is hard and why don't we give some extra dollars there to make this transition easy. What we see with some employers, this is a more common thought process, a lot of employers gravitate towards it, is do I find what the ICHRA can buy in the individual market and subsidize at that level?
Josh Miley :
Meaning our plans cover this today and this may be 80%, 85% of your healthcare costs. The rest being made up by deductibles and copays. If I can find something similar on the market, so pays 80%, 82%, why don't we target a subsidy that will allow you to buy that entirely in year one? The good news is you can buy these plans maybe with no premium because the ICHRA paid for the entire amount and then we'll see where year two goes. Maybe year two we hold it flat or we increase it by 2% and we know the market's going up by 5%. So part of this savings number is what you're trying to achieve. We know we can lower the base by 12%. What you then do with that as an employer becomes part of your strategy to say, do I give you more in year one to to make this comfortable for you or how do I do it?
Josh Miley :
And so that becomes the conversation for a large employer this past year is actually overtly not save money. What they said was, we know what we're going to subsidize going into 2026 anyway. Like if you saved it on the group plan contributions, were going up by this and we were gonna change that so we, we know we're gonna put this amount of money out and they converted that to an ICHRA whether you were in the ICHRA or not. We as a company are theoretically gonna give you the same amount. That was enough money that the individuals in the state where they did this could go buy gold plans and in many cases platinum plans, these are richer plans on the individual market. They could buy 'em for free. They went from the employer side where they had deductibles copays and they had to pay a payroll deduction.
Josh Miley :
They had money taken outta their paycheck to go into the individual market. And because the employer said, I'm gonna give these savings to you, they were able to buy higher price plans for free and now there really was no payroll deduction and they got the same type of deductibles, copays, and coinsurance. So day one the employer won as well because these are notional accounts. So if the employee doesn't use it, it goes back to the employer, anyone that bought a lower cost plan 'cause it was the right answer for them, that money just went back to the employer anyway. So we saw 99% of employees saved money and the employer saved about 10%. So, and that was with the intention of not saving anything, they still saved about 10%.
Nina Krammer :
Just in thinking about this specific client that you just mentioned, is there any kind of analysis or serving that's done before implementing an ICHRA, uh, at the employee level, what their perceptions might be and then post-enrollment, do you have any information that you can share there?
Josh Miley :
We don't have the specific metrics but we've done it and I can share you directionally what we hear and I can tell you some things to avoid as an employer going down this path. It is pretty common for an employer to want to share the change or you're going from this world to this new world. And let me tell you all about this new world. If you think about how we shop today on the group side, that's not how it works. On the group side, somewhere around August or September we get an email or we get a PDF file or something that says, here's how your plans are changing and here's how the premiums are changing and here's how your payroll deduction is changing. What they really want to know is what does this mean for me? Are they better? Are they worse? Do I save money?
Josh Miley :
Do I lose money? And I would encourage employers to start with that because that changes the question that you asked. Nina changes based on where you start. So when we've done the surveying for employers that have started with, let me tell you why we're doing this. Let me tell you philosophically what this means and let me tell you what this role is for you. And the role is for us, the angst and the nervousness by employees was high. And then they would see the number in October and November. They would say, wait a second, I can buy all these gold plans or platinum plans and I had a payroll deduction. Or I have one now and next year I won't have one 'cause this allows me to buy all this. Oh well that's not that bad. Maybe as you get into the year and if you have life event changes and things like that, maybe you're a little frustrated because your employer could have dealt with that.
Josh Miley :
Now they can't as much. So you scared them upfront then you made them happy. And then for a small segment of, of these individuals that have to deal with insurance in a different way, they may be frustrated at a point in time, but over 12 months they're not necessarily frustrated. They're no more frustrated than how they are today. We look at longitudinally surveying people. What I would say is if you start with here's what we're doing and a general statement around why we're doing it and what this means for you, the employee, meaning we think you're gonna save money, have more choices and more options and why we're doing this. We're not an insurance company. We make widgets. Why are we managing insurance Like we're an insurance company. I think when you say that to employees and then show them the financials, the acceptance rate's a lot higher. It doesn't mean it's some panacea that come January and February when the engine's all working that they're not gonna have frustration points. But you've met them where they are.
Nina Krammer :
Aside from not scaring employees ahead of time, what other piece of advice would you give or one piece of advice you would give employers who are starting to explore an ICHRA?
Josh Miley :
ICHRA is a tool. It may not be the the end all solution. So one of the things that I will say to employers is they naturally think, well wait a second, I have 5,000 employees. I'm not moving 5,000 employees to ICHRA. That sounds crazy. Okay, well would you move 500? Would you move a thousand? 'cause that's what you can do with ICHRA. You could say in state X or for manufacturing site Y, whatever makes sense to you from a business standpoint, I'm going to move those individuals to an ICHRA and I'm gonna leave others on a group plan. And the question's gonna be, why would I do that as an employer for a couple reasons. One, you're testing something new and your nervousness about testing on 5,000, you just reduced the risk of doing that. Two, you're going to save money. We're going to show you the analysis for whatever state that we mutually agree makes sense.
Josh Miley :
And if that state can save you $2 million 'cause you moved a thousand people, you're probably going to say, wait a second, me as an employer can save money. My employees in that state are likely to save money. I'm giving them more choice. And as the market evolves, if I can do this in Georgia, but maybe I have people in West Virginia, which isn't a great state over time, now I can maybe influence the state of West Virginia to do that. Or as the state of West Virginia comes online in a more effective way for ICHRA and the individual marketplace options there, I can tap into that because I've already done it. I've already set up the files and the feeds and I've already communicated and I know what it means and I've surveyed like I've done all these things, I'm ready to go as the market evolve.
Josh Miley :
So when I say it's a tool, it doesn't have to be the total replacement. It can be the, I'M testing it, I'm watching it, I saved the money, I proved to leadership, it works. Employees didn't freak out, they saved money. So I've proved that it works as the market evolves, which it will over the next two to three years, you're ready to go. Or maybe it's never, if you think about the dynamic that a large employer has with pension plans, many employers still have pension plans. They're just grandfathered or limited and then they have a 401k for others. You could see a scenario in the future for large employers where maybe it is ICHRA for 10%, 50%, whatever the number is, and it it's grouped for others. Maybe it's a new hire strategy versus a legacy employee strategy. There's ways you can look at it. I think we naturally go to it's all or nothing. And right now it's anything but that. It is generally never all, it's generally classes, which is specifically what the regs call them. So a segment would be a class in the regs. A lot of employers are looking at class based strategies, which could be location, it could be part-time, it could be hourly. So you could start to cut your population that way and test it in a way that makes sense for you.
Nina Krammer :
So long story short, I'm hearing scalability.
Josh Miley :
Yep.
Nina Krammer :
Flexibility, cost savings, risk reduction. Am I missing anything?
Josh Miley :
I think you hit the big ones. They're all great by themselves. I think part of it is also somewhat philosophical for employers as well, which is, am I an insurance company? I'm not. And I spend a lot of time, effort and energy managing risk managing health, managing employee perceptions. I don't do that for your auto policies. Why am I doing this? And I know it comes from the right spot, but that's not the business that you're in. And if there's a better answer for you, the employer and a better answer for employees philosophically it's worth exploring.
Nina Krammer :
Traditionally we think about benefits being evaluated by HR personnel. Have you had any experiences where you're getting say like A CFO or other departments who might not actively be involved in benefits selection or evaluation getting involved in these ICHRA discussions?
Josh Miley :
Yeah, I would say indirectly for a number of large employers, the head of total reward or the head of benefits may reach out and say, I was asked about and maybe the CFO or the CEO read about it, heard about it and is asking about it. What we're also doing with our health group benefits colleagues on the brokerage side and the consulting side is to just make sure there's awareness. Because the last thing we want is a benefit manager being caught off guard. What I say to a lot of HR professionals is at least have it as a bookend. If you think this is never going to be right for me, for whatever reason, you know your workforce better than we do. I can look at all the math in on the world. But if you feel that way, that could be the right answer.
Josh Miley :
At least have it as a bookend to say to your CFO, Hey, I can do these things. I can change networks and deductibles and whatever my strategy is for GLP ones, but I also have this thing out there that, and at least show the thought that you went through it and at least let your leadership team make the decision on it. So I would say the demand now is probably coming from finance and the C-suite in terms of coming through HR to ask us our strategy outward to benefits and to HR is to say whether you think it's right or not, at least know about it. I think it's kind of where we are with with HR.
Nina Krammer :
Josh, I feel like I could ask at least 50 more questions about ICHRA. Yeah, we don't have that kind of time. Yeah. So before we round out, is there anything that I haven't asked that you feel that we should talk about? Still,
Josh Miley :
It can take time to evaluate and certainly take time to implement an ICHRA. So give yourself plenty of runway to do it. If the answer is that you're evaluating something for 2027 time's now, there's some urgency around getting that done and showing leadership and then ultimately implementing, typically starting past July for an implementation is going to be impossible. So if you're thinking about 27, the time is urgent. Now if you're thinking about 28, the time is probably still now to give yourself the runway to to look at it for 2028. You just give yourself some more breathing room maybe I would say the time's now, regardless of whether it's 27 or 28, just give yourself some patience there in the conversation 'cause it is new. And give yourself some patience there in the conversation. 'cause implementation can take a little bit.
Nina Krammer :
Thank you so much, Josh for your time. I appreciate it. And for any of our listeners who would like to schedule time, either reach out to your WTW consultant or visit solutions dot via benefits.com/contact to fill out the form and we can get that call going for you.
Nina Krammer :
You've been listening to The Via Benefits Exchange. For more information about Via Benefits and the solutions we provide, visit via benefits.com. That's VIA benefits.com.