In our 31 December 2024 update, we explained that that there are different factors which may give rise to variability in the assumptions being adopted by different companies, as well as a number of complex issues for companies to consider when selecting appropriate actuarial assumptions for accounting purposes. Whilst the issues under consideration will typically be specific to each company, in recent times many companies will likely have had to consider the following areas:
- Uncertainties relating to the Virgin Media v. NTL Pension Trustees judgment, and the implications of the recent UK Government announcement regarding retrospective confirmations
- Surplus considerations given improvements in funding levels (primarily driven by rising discount rate assumptions) and the changing regulatory landscape around the availability of any surplus to employers
- Changes in life expectancies, in particular the longer-term implications of the COVID-19 pandemic as well as other socio-economic factors and the recently published CMI 2024 mortality projection model
The above list is certainly not exhaustive, but it does highlight the different types of issues companies are having to think about as part of their accounting processes, as well as highlighting the importance of carefully selecting appropriate actuarial assumptions when it comes to valuing pension obligations.
Key assumption trends
Discount rate assumptions
The discount rate assumption is used to place a value on the expected benefits payable over the lifetime of a pension scheme. There has been a notable increase in the discount rate assumptions being adopted over the year, driven by the rise in yields on AA-rated Sterling corporate bonds over that period (a similar trend has also occurred with yields on UK Government bonds, "gilts").
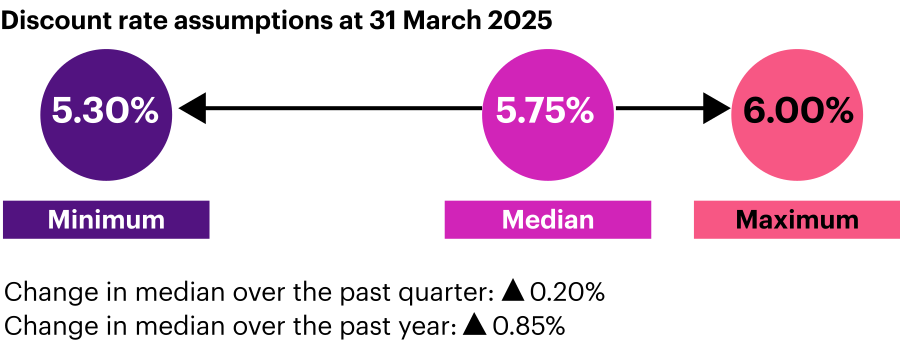
Discount rate assumptions at 31 March 2025
Inflation assumptions
Inflation assumptions are used to estimate how members' benefits might increase in the future. There has been a slight decrease in inflation assumptions over the year, with this typically reflecting the change in investors' views of future inflation (as the assumption is typically set with reference to market data).
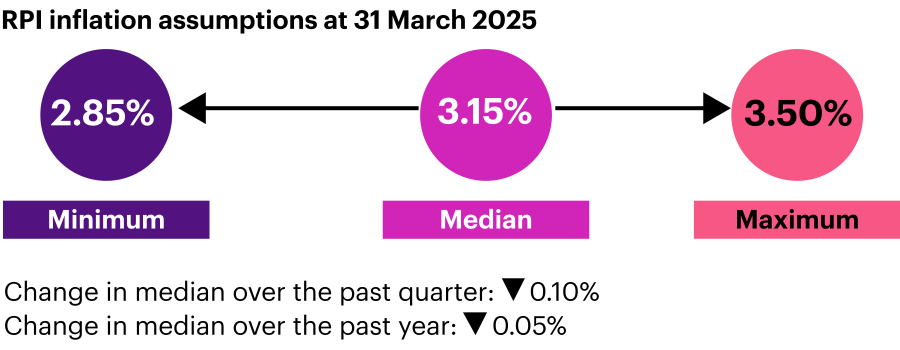
RPI inflation assumptions at 31 March 2025
Life expectancy assumptions
Assumptions around life expectancies estimate how long benefits will be paid to members and their dependants. There has been a slight decrease in life expectancies. This was driven by the majority in our survey adopting the latest CMI 2023 mortality projections model. This model places slightly more weight on the higher mortality seen during the pandemic, slowing down the projected rate of future improvements in life expectancy compared to the previous model, CMI 2022. We expect to see this reverse by the end of the 2025 as the recently published CMI 2024 model is adopted reflecting the latest post-pandemic mortality improvements.
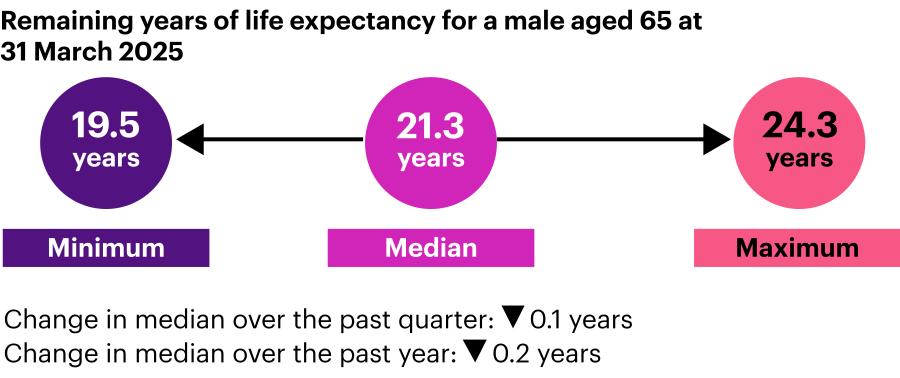
Remaining years of life expectancy for a male aged 65 at 31 March 2025
What does this mean for UK pension scheme disclosures?
Taking the above into account, we would generally expect liability values to have reduced over the year. In terms of the net balance sheet position, however, the extent to which this will have changed will depend on the specific circumstances of schemes (in particular, the investment strategy adopted over the year).
Contacts

Get the latest pensions news
Join the conversation on LinkedIn and keep up to date on industry trends, insights and thought leadership.