

Defined benefit (DB) pension plans benchmarking
DB plan sponsors entered the second half of 2026 with a stronger financial position than at the start of the year.
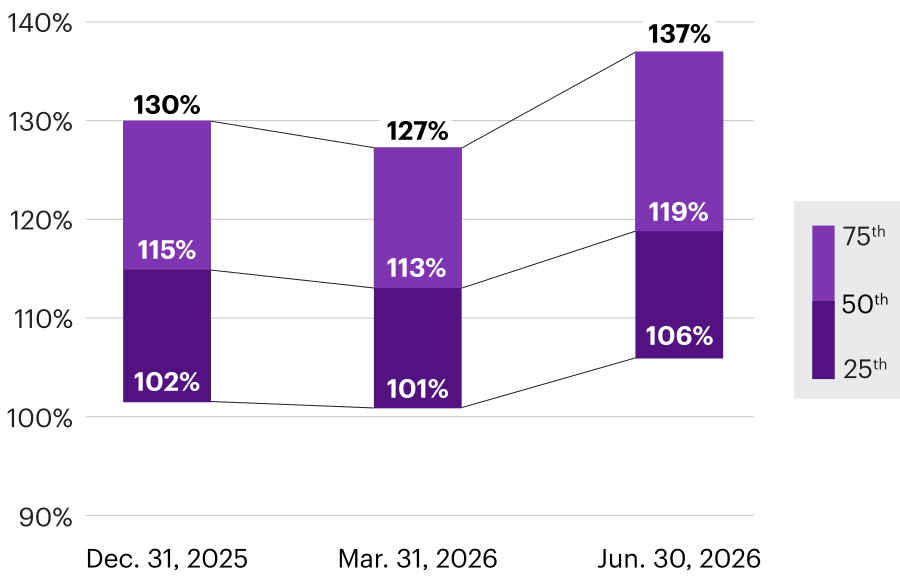
Evolution of solvency positions in 2026
The funded status of Canadian DB pension plans improved significantly during the first half of 2026, recovering from the market decline experienced early in the year. Depending on plan maturity and the degree of investment de-risking, solvency funded positions for the DB plans for which WTW is the appointed actuary in Canada increased by approximately 4% to 7% over the period. Strong equity market performance was the primary driver of these improvements, while interest rate movements had a more limited impact given their relative stability during the first half of the year. The current distribution of funded ratios does not yet reflect recent mortality developments in the Canadian pension market, as described in the next section.
The strong funding recovery observed during the first half of the year highlights, for the second year in a row, both the resilience of many DB plan funded positions and the value of a disciplined risk management framework. For plans with meaningful surplus, sponsors are increasingly reassessing long-term investment strategy, the role of surplus optimisation, and the timing of potential buy-out annuity purchases. In this environment, annuity purchases are best evaluated as part of a broader funding and surplus management strategy rather than as a stand-alone de-risking transaction.
Mortality assumptions update
Mortality assumptions are a central input in DB plan valuations and pension risk transfer analysis. On March 11, 2026, the Canadian Institute of Actuaries (CIA) released a new Canadian pensioners’ mortality research report, including updated mortality tables intended to reflect the mortality rates of Canadian retirees and the introduction of stand-alone surviving spouses mortality assumptions. Together with the CIA’s April 11, 2024 research paper on mortality improvements, this work is expected to influence Canadian pension plan valuation and reporting assumptions in future periods.
Plan sponsors should consider how updated views of pensioner longevity may affect reported liabilities, surplus levels and risk transfer strategies. While the new mortality information may increase reported pension liabilities, its impact on annuity purchase cost is expected to be more limited:
The release of the new mortality tables reinforces the importance of plan-specific mortality calibration. Unlike the 2014 tables, which distinguished between public- and private-sector populations, the new tables are organized by mortality profile. As a result, sponsors will need to select the most appropriate base table and calibrate it to reflect their plan's characteristics. We estimate that over 80% of WTW-supported plans will customize their mortality assumptions using socio-economic indicators, demographic characteristics and professional actuarial judgment, with larger plans also incorporating their own mortality experience where credible.
Group annuity market
We continue to expect full-year market volume broadly in line with 2025, at around $7B.
Key highlights
Implied spreads on non-indexed group annuities, as published by the CIA, increased from 110 bps above Government of Canada 10-year yields at December 31, 2025, to 120 bps at June 30, 2026, aligning with the historical average. Actual spreads offered by insurers during the first half of the year were often higher.
Absolute annuity yields remained attractive, continuing to hover just below 5% in the first half of the year. These levels remain well above pre‑2022 averages, resulting in lower absolute annuity costs relative to long‑term historical benchmarks.
Updated mortality assumptions, combined with implied annuity yields that often exceed yields available on high-quality AA corporate bonds, have made balance sheet gains on annuity transactions more common. While balance sheet gains remain more difficult to achieve for indexed annuities because of the inflation premium charged by insurers, the update of the accounting mortality assumptions will improve the likelihood of achieving such gains, particularly for larger transactions.
Given the relatively low level of expected total market volume this year, we expect pricing to remain competitive for the remainder of 2026, assuming insurer capacity and broader market conditions remain supportive.
Insurer participation in 2026 has remained strong across a range of transaction types, including smaller transactions and more complex placements involving a high proportion of deferred vested members or intricate plan provisions.
As was the case in the past, larger transactions continued to attract the strongest insurer engagement, resulting in more competitive pricing and reaffirming that scale remains a key driver of market competition.
The proportion of deferred vested members included in annuity purchase transactions has increased, particularly among repeat buyers. As a result, data clean-up and bulk lump sum campaigns, completed before or alongside a transaction, can be increasingly valuable in improving the profile of the group being insured and therefore help increase participation and reduce premiums.
We expect activity to increase in the second half. Sponsors that focus early on transaction strategy and data readiness are likely to be better positioned to attract insurer engagement.
Discharge legislation for Alberta and Federally regulated plan members could be in force as early as fall 2026 after regulations are enacted.
Alberta and Federal regulators already provide some administrative relief for buy-out annuities, but a formal discharge would further reduce “boomerang” risk — the risk that a plan sponsor remains responsible for insured benefits after a buy-out transaction.
If implemented, these changes could inform new risk transfer strategies for sponsors with members in those jurisdictions.
About the WTW Group Annuity Purchase Team
The WTW Group Annuity Purchase Team has extensive expertise and experience in Canadian group annuities, helping to provide the best outcomes for our clients:
#1firm in Canada for the last six years in annuity placement volume, representing over 40% of the total market and 80% of the indexed annuity market over the last two years.
18experienced specialists who are part of a growing team at the forefront of innovation.
$20B+in liabilities transferred through group annuity purchases, representing over a third of the total historical volume in Canada, including multiple $500M+ transactions.
500+robust and comprehensive financing strategies for pension plans developed by our team.
Authors
Manage preferences
Subscribe to receive our latest insights