

Since 2019, commercial insurance buyers in North America have been searching for a break in the clouds. The second half of 2022 has ushered in a new environment that provides a brighter picture, one with improved pricing conditions, coverage, and capacity for many commercial lines of business. This is not to suggest it is time to celebrate soft conditions, but it does mark demonstrable improvement in the market. That said, one of the lone holdouts for a hard market, commercial property, is facing material headwinds, and the industry as a whole must mind the upward pressure that several macro factors may have on rate.
Every buyer is challenged to accurately assess and present replacement cost values that go up as the cost of labor and materials goes up.
The first of these factors is inflation in its many forms. The Consumer Price Index and slipping purchasing power may headline the news, but there’s also wage inflation, medical inflation, and, as anyone in the casualty world will tell you, social inflation. These factors are raising loss costs. On the property side, every buyer is challenged to accurately assess and present replacement cost values that go up as the cost of labor and materials goes up. Carriers, meanwhile, must recalibrate portfolios based on their growing potential exposure.
On the casualty side, nuclear verdicts fueled by social inflation continue to push tort costs and, subsequently, claims costs higher. But insurers have been dealing with these forces for some time now, and pricing adequacy is beginning to turn the market for buyers—rate reductions are possible and even approaching double digits in the best scenarios.
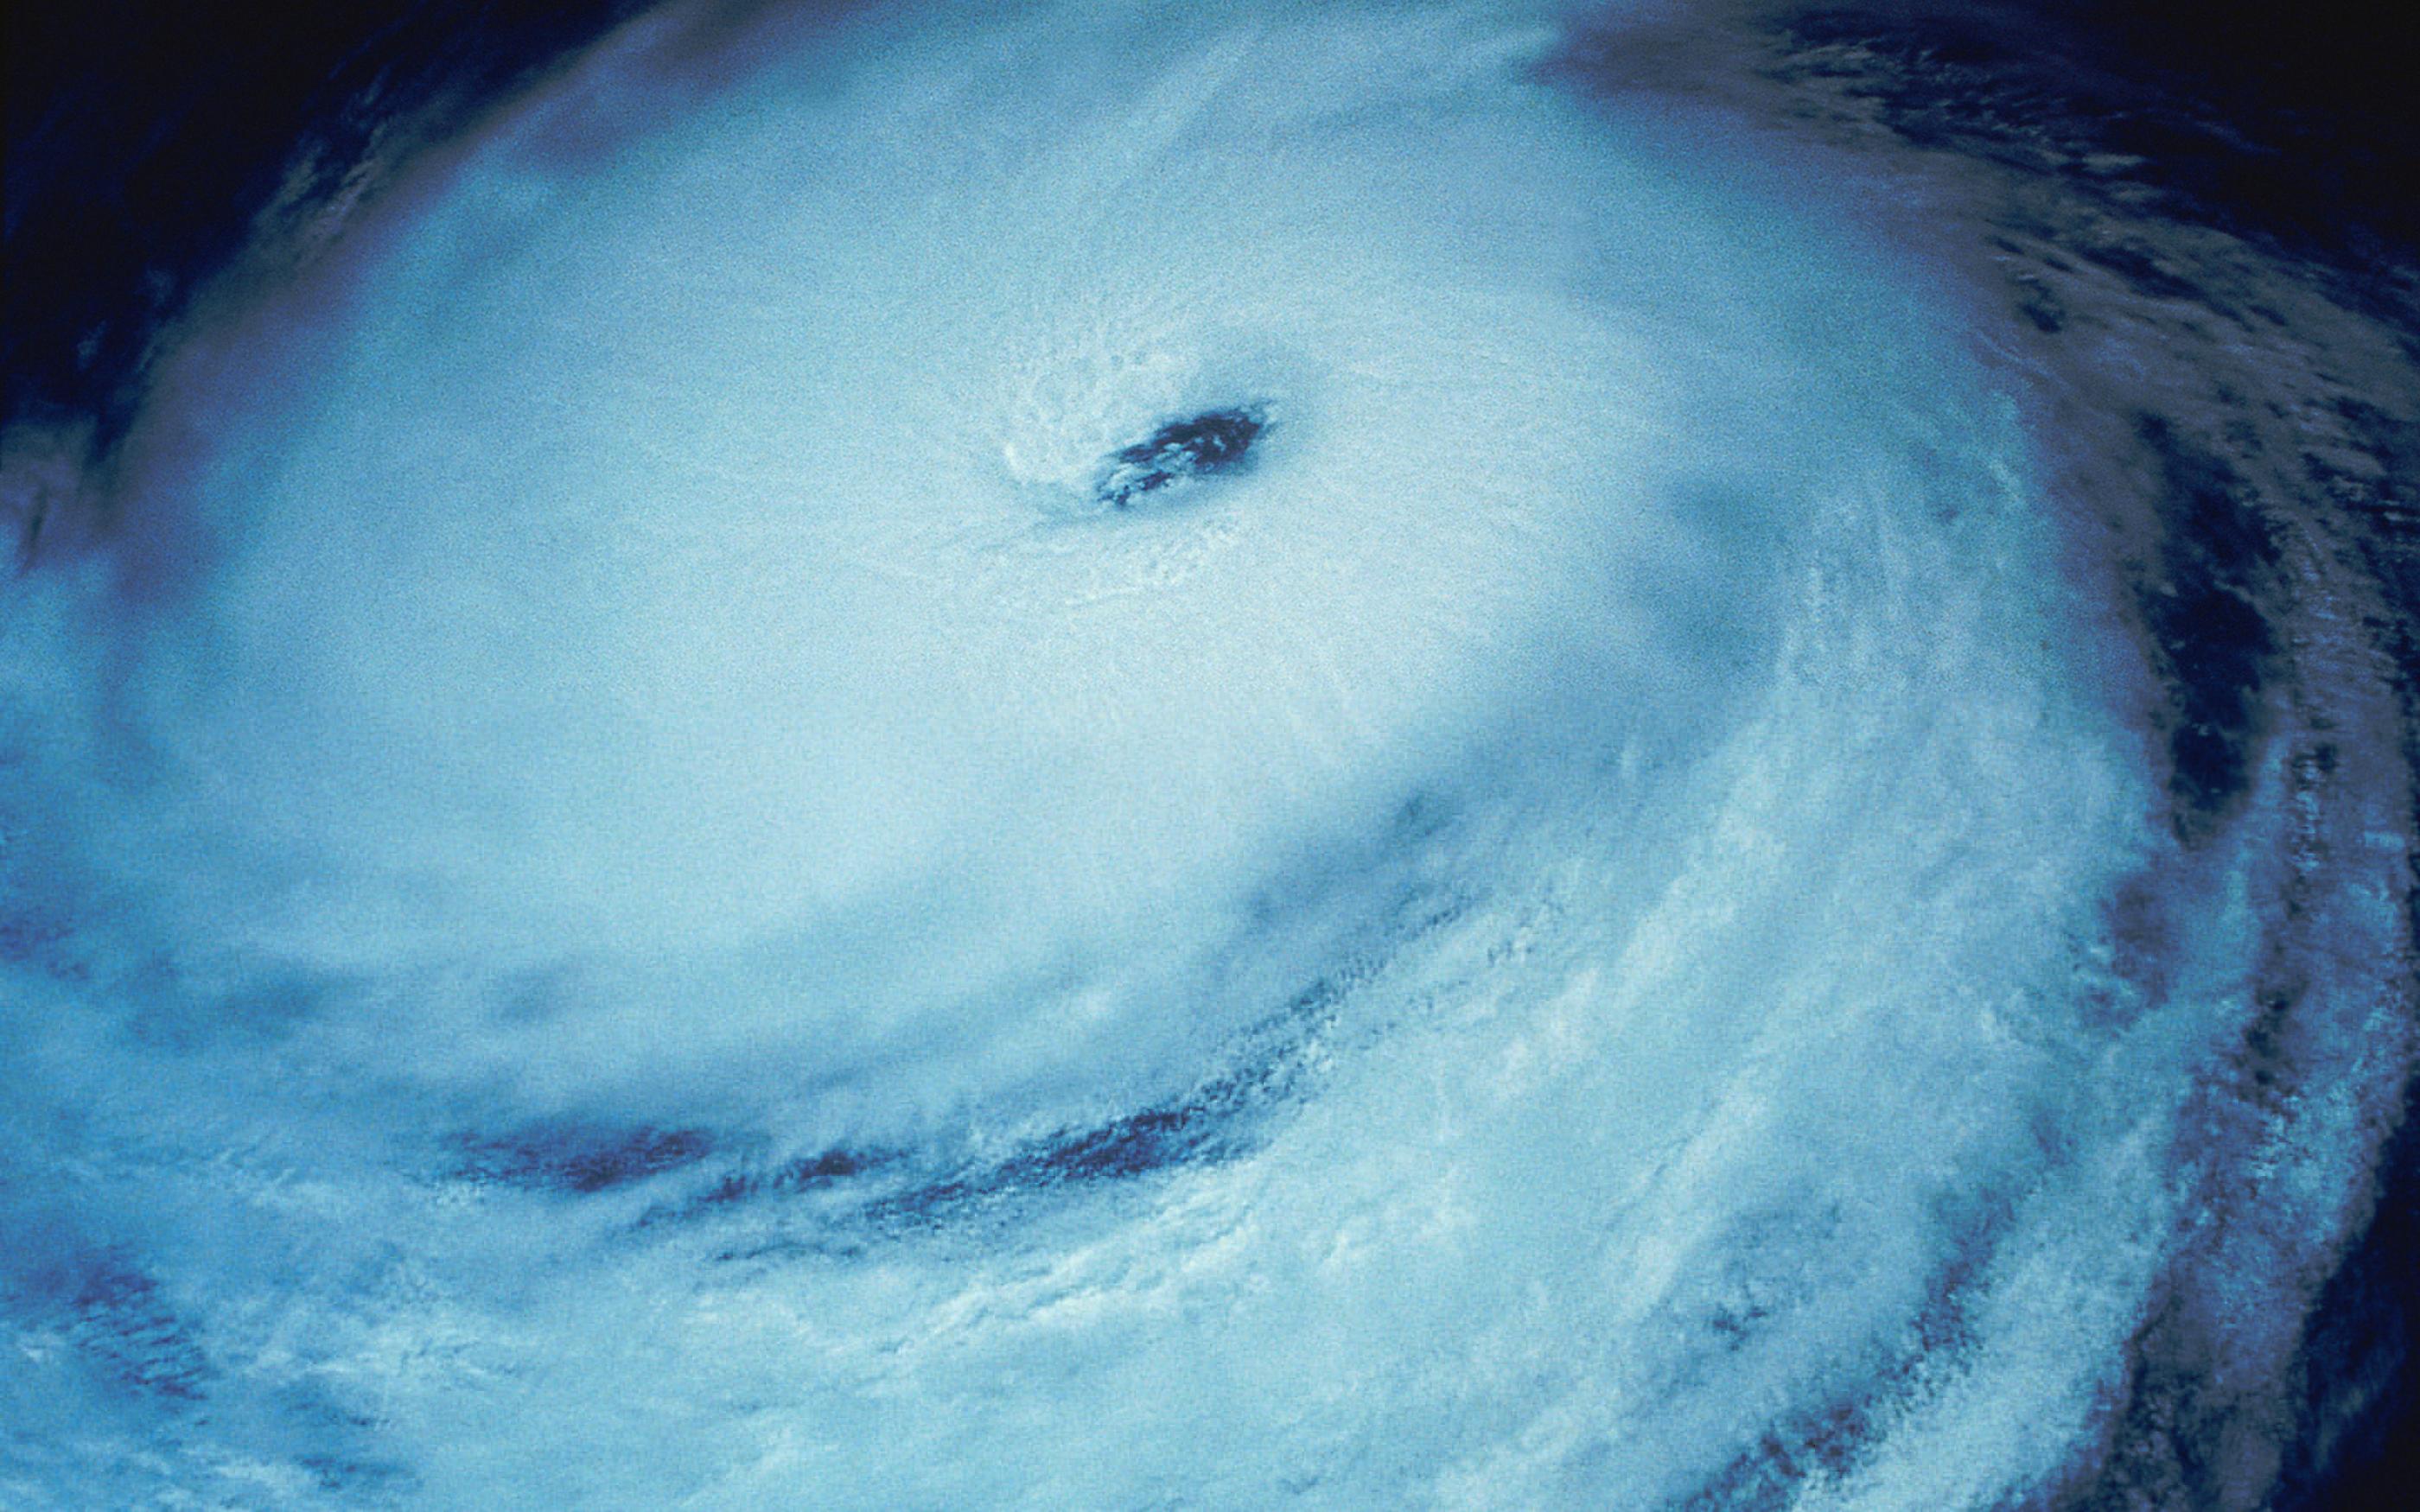
Property insurers have rekindled their tenacity to drive rate. This retrenchment is not solely driven by inflation but also by the continuing procession of loss events pushed by the extremes of weather. This brings us to the second macro factor we are focused on: Hurricane Ian.
Extreme weather of all kinds strikes in places where we haven’t seen it before, and places we’ve seen it all too often.
In addition to the personal tragedies that resulted from the punishing landfall, this was a big, albeit unique, loss event. While ultimate economic costs will take some time to play out, there is no doubt that Ian losses lean heavier on the personal lines side than the commercial side. However, the commercial response has been swift and dramatic. With retail insurers making immediate adjustments to catastrophe capacity and rate, reinsurers are telegraphing grim renewal conditions for 2023, which would compound the rate and structural pressures we experience today.
Whatever the fallout from the 2022 hurricane season, natural catastrophes loom large for our industry. Wildfire, not high on our lists a ten years ago, remains on our lists now. Extreme weather of all kinds strikes in places where we haven’t seen it before, and places we’ve seen it all too often.
Here are some highlights from our 2023 predictions:
So, while the grip of the hard market is loosening, buyers are not yet free from it. There are opportunities in the marketplace, which puts an increasing emphasis on the importance of analyzing and understanding your risks and being prepared to present them clearly and effectively to underwriters.
Use all the tools available to you, especially the analytic tools that steadily improve in their predictive value and ease of use. Work closely with your risk management partners — carriers and brokers — to make the most of the opportunities that do present themselves. Availing yourself of these resources will help make you and your organization all the more ready to face the ongoing challenges that lie ahead.
For more insight on how you can prepare for a challenging marketplace, contact your local WTW representative.
Major product lines
Disclaimer
Willis Towers Watson hopes you found the general information provided in this publication informative and helpful. The information contained herein is not intended to constitute legal or other professional advice and should not be relied upon in lieu of consultation with your own legal advisors. In the event you would like more information regarding your insurance coverage, please do not hesitate to reach out to us. In North America, Willis Towers Watson offers insurance products through licensed entities, including Willis Towers Watson Northeast, Inc. (in the United States) and Willis Canada Inc. (in Canada).
Download
| Title | File Type | File Size |
|---|---|---|
| Insurance Marketplace Realities 2023PDF | 10.9MB |